How Higher Mortgage Rates Are Changing Real Estate Investing
Originally published on October 22, 2026
“Higher rates don’t eliminate the real estate opportunities.” – Kyle Paxton
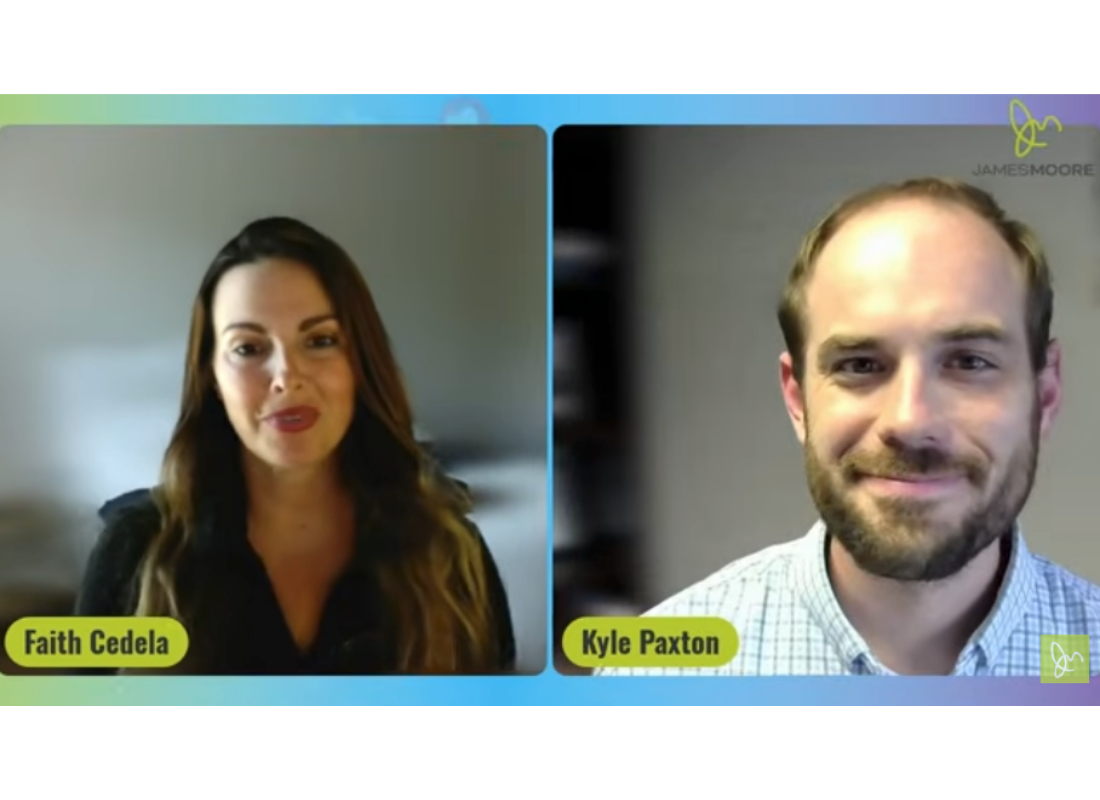
Higher mortgage rates are forcing real estate investors to rethink how they buy, finance and plan around their properties. In this episode of Your CPA’s Take on Real Estate, Faith sits down with Kyle Paxton to break down a recent MarketWatch report showing mortgage rates at their highest level this year.
The discussion covers three questions investors are asking right now. First, are investors finally accepting that rates will stay higher for longer? Second, how should buyers assess deals in today’s financing environment? Third, which tax planning strategies matter most when borrowing costs rise?
Kyle explains why underwriting the debt first makes more sense than starting with purchase price, and why the planning around depreciation matters more than the deduction itself. He also covers interest deduction limits, interest tracing on refinances, real estate professional status, 1031 exchanges and qualified opportunity zones.
Resources
Your CPA’s Take on Real Estate
Your CPA’s Take on Real Estate on YouTube
Watch: Higher Mortgage Rates Are Changing Real Estate Investing
Transcript
[00:02] Faith: Hi everyone and welcome. I am here today with Kyle Paxton. Hi Kyle, how are you?
[00:02] Kyle Paxton: Hello. Always a pleasure. Good to see you.
[00:02] Faith: Happy Monday. So we just wanted to hop on quick today because we’re going to talk about some trending news and what’s going on in investment real estate and everything manufacturing.
[00:22] Faith: I mean, you kind of cover it all. The article that we’re talking about today, I’m going to link below on this live, so if people want to read it they can, and then I’ll repost your thoughts on it. It’s on marketwatch.com, and it’s basically that mortgage rates have climbed to 6.55%, the highest level this year, driven by inflation concerns and geopolitical uncertainty.
[00:44] Faith: Higher borrowing costs continue to pressure affordability and slow home sales. So the title today is the great real estate repricing: what higher interest rates mean for investors. And the first question is, are investors finally accepting that higher for longer interest rates are the new reality?
[01:11] Kyle Paxton: Oh, Faith, we blinked. I saw at the end of last week, Freddie Mac’s latest weekly reading was 6.66. So we’re climbing even more here. Crazy town. Anyway, to answer your question, yes, I do think investors are finally accepting higher for longer. From what I’m seeing through conversations, the acceptance is showing up in action and repricing rather than through optimism.
[01:39] Kyle Paxton: I think for several years investors have been treating the elevated rates as more of a temporary bridge: acquire a property, use short-term debt, stabilize, refinance. That assumption’s becoming harder to defend. The Fed’s held its policy rate steady through 2026 at 3.50 to 3.75. Freddie Mac, like we just said, is at 6.66.
[02:05] Kyle Paxton: Future Fed cuts don’t guarantee an equivalent decline in mortgage or commercial borrowing rates, right? And so we’re seeing investor purchases fall to the lowest level since 2020. I think there’s still a disconnect here between sellers’ pricing and what buyers are willing to stomach.
[02:31] Faith: Absolutely. How would buyers evaluate deals in today’s financing environment?
[02:31] Kyle Paxton: It’s a good question, right? Real estate’s a cash gig. So I think it just comes back to cash flow. I like the idea of paying attention to the debt first. I think we fixate on what a property is worth and then we kind of backfill that with how we make the financing fit.
[02:58] Kyle Paxton: I think underwriting the debt first makes sense here. So we’re evaluating the debt service coverage and using current interest rates, like we said before. I don’t think we can count on that refinance in the next couple years. So we’re really looking at the cash flow after taxes, insurance and reserves, making sure we can service the debt and meet any covenants we have in order to keep that afloat.
[03:22] Kyle Paxton: And then something I’ve been talking about a lot in these video series recently is really making sure we’re being truthful about the downside, right? I’m very pro-investing in real estate, but there’s a lot of risk involved in investing in real estate right now.
[03:43] Kyle Paxton: In charting out the refinance, I think we have to be comfortable refinancing at today’s rates, not at your assumed basis point decline. Would I still own this property if rates don’t decline before the loan matures? To some degree, we might be there, right? Another thing that we’ve talked about a lot on our YouTube channel and amongst our James Moore real estate team is being mindful of replacement financing too.
[04:19] Kyle Paxton: That means being creative about how we’re financing deals, because maybe that traditional loan isn’t the best way to fund the deal. These are all things to be considering, and I think they really come into play when evaluating deals, more so than just the purchase price, right?
[04:38] Faith: Yeah, absolutely. And the next one: does depreciation become even more valuable when borrowing costs increase?
[04:38] Kyle Paxton: I love this question. I don’t know if it becomes more valuable simply because interest rates rise. I think the planning component around depreciation definitely becomes more valuable, because it comes back to cash flow.
[05:04] Kyle Paxton: The timing of that depreciation deduction can have a significant impact on cash flow. You and I have talked a lot about how depreciation is just a timing difference at the end of the day. When you hold a property, you get the deduction at some point, and then when you go and sell, you potentially have the recapture if you’re not doing a 1031 exchange or something like that.
[05:25] Kyle Paxton: So as a whole, maybe the deduction’s not more valuable, but the planning around it is. And 100% bonus depreciation is available right now for qualified property under the One Big Beautiful Bill. Cost segregation studies are everywhere. I’m talking about them all day, all the time. So I think, interest rates aside, it’s a great time to take advantage of depreciation.
[05:48] Kyle Paxton: But I do want to really emphasize the planning around it. I talk to a lot of real estate investors who say everyone else is doing cost segregations, so they need to as well. But there’s 15 different catches, caveats, things that you need to work through in your analysis to make it actually worth it.
[06:06] Kyle Paxton: So to take a step back, we’ll say it does become more valuable, but I want to emphasize the planning component around it.
[06:06] Faith: Yeah, absolutely. So the last question we’re going to talk about today is right in your area of expertise, and I want your opinion.
[06:27] Faith: What tax planning strategies become more important in a higher rate environment?
[06:27] Kyle Paxton: We talked about cost segregation and bonus depreciation. I do still think that’s number one. To me, that’s low-hanging fruit. There is a lot of work that goes into it, but it’s fairly straightforward stuff. The other thing I want to bring back to the table in this conversation is that with higher rates, you are paying more out in interest expense, right? That applies to your investment properties whether you’re holding them as a rental or
[06:58] Kyle Paxton: using them as part of your commercial business, whatever the fact pattern is. On average we’re going to be having higher interest expense right now. There are limits around the amount of business interest you can deduct, particularly for higher leverage partnerships. Your classic real estate fund that has a lot of limited partners can fall into this trap.
[07:21] Kyle Paxton: So planning around making sure we can actually take the interest deduction, and the strategies around getting out of the limitations that could cause us issues, is very important. The other thing I want to emphasize here is interest tracing. Generally speaking, the deductibility of your interest related to real estate follows the use of those borrowed proceeds.
[07:50] Kyle Paxton: So just because we have a debt doesn’t necessarily mean that we can take the interest deduction. With refinances, if you take a refi and turn around and distribute funds to your partners, that can cause issues with the deductibility of interest. So again, it just gets back to good planning. Thinking through the real estate professional status buckets is also very helpful in these conversations, making sure we get maximum deductions in our tax planning.
[08:25] Kyle Paxton: The other thing I’m still seeing come to the surface a lot is the more classic tax deferrals related to real estate, like Section 1031 like-kind exchanges. And another piece that’s come back into the fold here is qualified opportunity zones and the gain deferrals when investing in properties in those zones.
[08:48] Kyle Paxton: I could go on all day, but for the sake of keeping our video short, we’ll stop it there. There’s plenty to do around tax strategies. I think the summary here is that higher rates don’t eliminate the real estate opportunities.
[09:04] Kyle Paxton: It just makes analyzing the cash so much more important, along with modeling out worst-case scenario and disaster assumptions.
[09:04] Faith: Absolutely. You’re giving hope in a pretty intense situation. I appreciate it. Well, it was great talking to you today, Kyle. We’ll come back and do more of these news updates, because I think it’s really interesting to get your opinion on these things. It can be very shocking when you see it.
[09:33] Faith: It’s nice to get an expert to dissect it. All right, Kyle, we will talk again soon. Thanks.
[09:33] Kyle Paxton: Always a pleasure. Thank you.
Watch the Full Episode
Rates may stay elevated for a while, but the investors who plan around cash flow, financing and taxes will still find opportunities. Watch the full episode of Your CPA’s Take on Real Estate to hear Kyle’s full breakdown, and subscribe for more news updates from the James Moore real estate team.
All content provided in this article is for informational purposes only. Matters discussed in this article are subject to change. For up-to-date information on this subject please contact a James Moore professional. James Moore will not be held responsible for any claim, loss, damage or inconvenience caused as a result of any information within these pages or any information accessed through this site