Why Small Teams Are Outpacing Big Firms with AI and Wealth Creation
Originally published on September 18, 2026
AI and wealth creation are becoming the same conversation. While most people are focused on what AI means for jobs, the bigger shift may be in who gets to build wealth, and how fast.
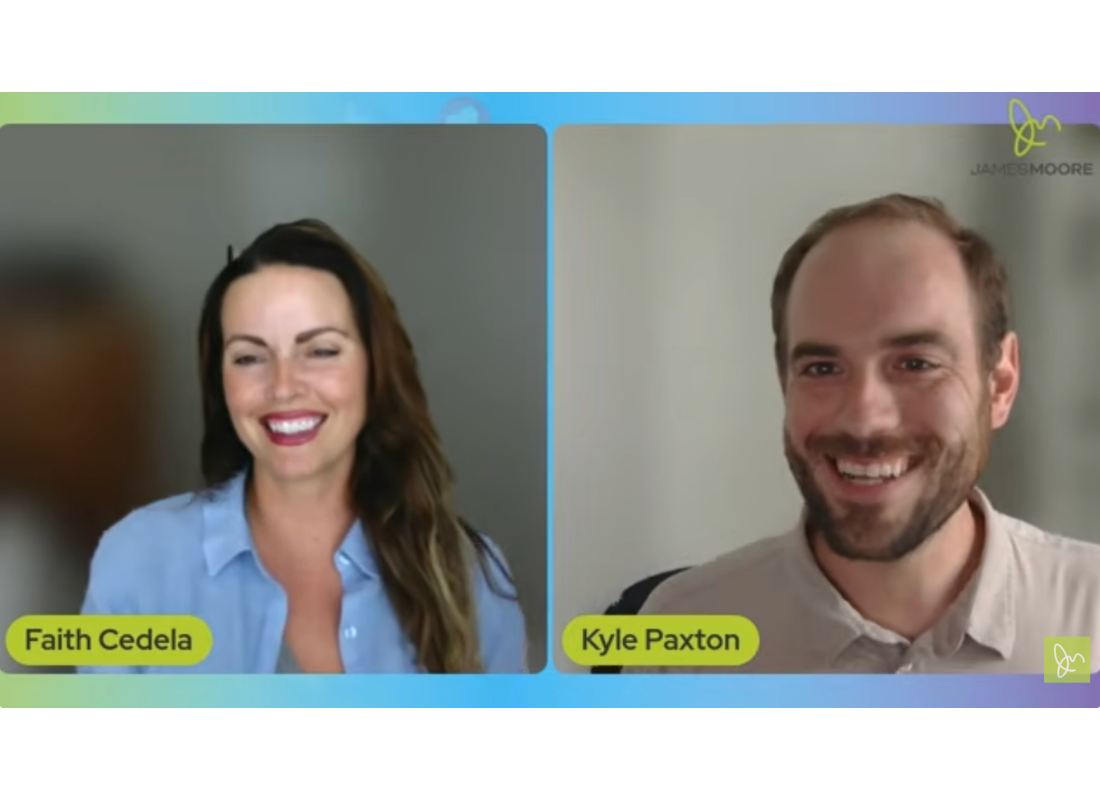
During a recent episode of Your CPA’s Take on Real Estate, James Moore CPA Kyle Paxton joined host Faith to unpack how AI is giving small teams access to capabilities once reserved for much larger organizations. That shift matters most for business owners trying to grow without the infrastructure that used to be required to compete.
Why Wealth Creation Is the Real Story
For years, building a meaningful business meant assembling a lot of infrastructure: people, systems, capital, and software. Small teams, especially those operating in a “family office” style setup, often carried a heavy load with limited support.
“What I’m seeing AI doing in that space is just compressing that friction,” Kyle said. “It’s giving the smaller teams access to bigger capabilities that kind of stretch more like larger organizations.”
That access changes the math on wealth creation. It’s not necessarily about saving money outright, since many of the tools involved carry real costs. The value comes from leverage: freeing up time so it can be redirected toward the highest and best use, whether that’s running a core business more efficiently or managing other income streams like real estate.
What This Looks Like in Practice
A few areas are already seeing this play out. Business owners are producing content, analyzing customer trends, building dashboards, drafting process memos, and summarizing contracts far faster than they could a few years ago.
“It’s making expertise more accessible,” is how Kyle described it, noting that AI is not a replacement for advisors but a way to get to a useful first draft faster and interpret information more clearly.
There are limits, too. If a business is starting from weak margins or messy data, AI will not fix that on its own. “You still need the business discipline we’ve seen successful historically,” Kyle said. “It’s just all of that is so much more accessible these days.”
The Industries Positioned to Benefit Most
A few sectors stand out where this shift is especially visible, starting with real estate and construction. Tasks like underwriting, lease data, property level cash flows, and construction budgets have historically been manual and time consuming. AI is helping distill that work into better dashboards and forecasting.
Professional services, healthcare, and manufacturing are also seeing administrative burden drop as data becomes easier to put to work.
What Business Owners Should Do Now
The advice for owners is practical rather than flashy. Start with your data. If it is not organized, AI cannot help you make sense of it. From there, identify your actual pain points instead of chasing the newest tool on the market, and start using AI in some form, even a small one, to build familiarity with what it can do.
Bringing advisors into the process matters too. CPAs and other advisors often have visibility across many clients and can help business owners understand what is actually working elsewhere, not just what sounds promising.
Watch the Full Conversation
This is only part one of a two part conversation between Faith and Kyle Paxton, CPA. Watch the full episode above, or catch it directly on the Your CPA’s Take on Real Estate YouTube channel, to hear the complete take on where AI is headed and what it means for business owners planning for long-term growth.
All content provided in this article is for informational purposes only. Matters discussed in this article are subject to change. For up-to-date information on this subject please contact a James Moore professional. James Moore will not be held responsible for any claim, loss, damage or inconvenience caused as a result of any information within these pages or any information accessed through this site.